MoMo - No.1 E-wallet in Vietnam
Revamp
Redesigned the Secured Payment screen for the first time in 5 years to reflect MoMo’s refreshed brand identity and reach the business goals.
Not interested in reviewing the UX process?
Khoyy
Payment Core
M_Service

Pay Later Growth
+
K
New Users
Quantitative Impact
+
%
Internal SoF Share
Figures adjusted to preserve confidentiality; magnitudes and directional trends reflect actual results.

Explore the process
Project Brief

Old Secure Checkout Screen
About MoMo
Launched in 2010, MoMo is proud to be Vietnam’s tech unicorn, offering a leading super-app financial platform that serves over 31 million users. It has become a cornerstone of the country’s Fintech and digital economy ecosystem.
Revamp Secured Payment - Overview
As the final step in the transaction flow, the Secure Checkout screen reassures users that their information is protected while allowing them to review and confirm key details before completing the payment.
After 5 years, the Secured Payment screen underwent its first redesign to meet the requirements of MoMo's new brand identity and tackle critical business issues.
At this stage of the funnel, a 1% shift in conversion translates to millions of transactions monthly — making even small design decisions disproportionately high-stakes.
Requirements
Redesigned the Secured Payment screen to align with MoMo’s new brand identity.
Target: Drive 300,000 new MoMo Pay Later activations via Secured Payment in 2025 — a business goal set by the Payment Core cell.
Balance design constraints: reconcile brand refresh requirements with Payment Core's growth targets and Risk team's guardrails on checkout funnel stability.
Base on Design Thinking
Design Process
Given that Secured Payment already had 5 years of production data and user behavior patterns, the team started with the Test phase — auditing the live screen, running tracking analysis, and identifying friction points — before looping back through Empathize and Define to frame the redesign problem.

khoi.nguyen
loi.truong
khai.tran
Dashed arrows represent iteration loops: insights from testing fed back into problem reframing, ideation, and design refinement.

What are the factors responsible for the problems?
Survey & Testing
Survey & Finding
To address the KPI of increasing new MoMo Pay Later activations from the Secured Payment screen, I didn't start with a solution — I started by asking why users weren't converting.
I ran a survey with 300 users that surfaced 8 raw friction signals. Three filters narrowed those down to the hypotheses worth testing:
Frequency filter (>40% of users mentioned it) → 5 candidates
Severity filter (blocks activation, not just annoys) → 4 candidates
Testability filter (can be isolated in a production A/B test) → 3 committed hypotheses
The three survivors: (1) Visibility of the Pay Later entry point, (2) Promotional messaging strength, and (3) Placement of the offer in user context.
Before redesigning anything, I ran A/B tests on the current screen to confirm which factor actually moved the needle. These tests diagnosed the problem — they didn't test a solution yet.
A/B Testing - Hypothesis 1
Timeline: 07/01/2025 - 14/02/2025
Hypothesis 1: Showing pre-approved credit limit to unregistered users will increase click-through on Pay Later CTA by making the offer's tangible value immediately visible.
Based on the hypothesis that users are more likely to take action when product information is clearly presented, we conducted an A/B test on two user segments (those who had not yet activated MoMo Pay Later) to evaluate the impact of showing the approved credit limit.
→ Results showed users who saw their approved credit limit had a click-through rate nearly 6× higher (13.41% vs 1.95%) than those who did not.
Disclaimer: To ensure confidentiality, the data has been blurred and adjusted.

Table 1: A/B Test Results – Impact of Displaying Approved Credit Limit to Unregistered MoMo Pay Later Users
A/B Testing - Hypothesis 2
Timeline: 07/01/2025 - 14/02/2025
Hypothesis 2: Users will be more inclined to open MoMo Pay Later if promotional labels are prominently displayed.
Users who saw the promo label had click-through rates 1.3× to 2.6× higher across 4 of 5 services — with Airline and Billpay showing the strongest lift (2.2–2.6×), while the Data service showed no lift. Promo label effect varied by service category — strongest on Airline/Billpay, none on Data. Further segmentation analysis scoped for follow-up.
Disclaimer: To ensure confidentiality, the data has been adjusted.

Table 2: A/B test results comparing click-through rate on Pay Later entry point, segmented by service and by whether the promo label was visible. Test window: 7 Jan – 14 Feb 2025 (~6 weeks).
Tracking Data - Hypothesis 3

Current MoMo Pay Later Widget Promotion at Secured Payment
Timeline: 07/01/2025 - 14/02/2025
Problem: Pay Later is promoted in a low-visibility position with weak messaging, making it hard to attract and motivate users to explore or activate the feature.
Hypothesis 3: Users on the Pay Later whitelist are more likely to register or use the service when they see clear product value and relevant offers at Secure Checkout touchpoints that match their needs.
Disclaimer: To ensure confidentiality, the data has been blurred and adjusted.

Table 3: Tracking CR click Widget Promote MoMo Paylater at Secure Checkout
Baseline tracking revealed the scale of the problem: of users landing on Secure Checkout, only 22.5% saw the Pay Later promotion widget, and just 0.09% clicked through — confirming the current promotion surface was functionally underperforming. This baseline became the floor against which Hypothesis 3's redesign was measured.

What are the factors responsible for the problems?
Define
User Persona

Problem Statement
Three friction points hypothesized from production data and stakeholder input:
1. Approved credit limit not visible → low trust, low activation.
Promotional offers lack visibility → low exploration.
Pay Later placement crowded & low-prominence → low engagement
Each became a testable hypothesis in the next phase.
Draft some viable solutions to tackle the situation!
Ideate
About the Solutions
After conducting A/B testing and gathering data from relevant stakeholders, I proposed a design that incorporates the following ideas:
Design Principles
How might we clearly present the approved credit limit to build trust and encourage users to activate MoMo Pay Later?
When users see their approved credit limit, it helps them feel more in control and confident in the product. This visibility reduces uncertainty and builds trust, which can increase the likelihood of activation. Without this information, users may hesitate or ignore the feature altogether.
How might we make promotional offers more visible and relevant to motivate unregistered users to explore MoMo Pay Later?
Promotions are a strong trigger for user interest and action, especially for new services. If promotional messages are hidden or vague, users are less likely to notice or feel compelled to engage. Making offers more visible and contextual can drive higher exploration and activation rates.
How might we improve the placement and messaging of MoMo Pay Later at checkout so it stands out and drives engagement?
Currently, Pay Later is placed beneath a crowded payment carousel with generic messaging, making it easy to overlook. Improving its visual prominence and using clearer, benefit-focused messaging can help capture user attention and increase interaction with the feature.
New Secured Payment Before Testing
Based on insights from Hypotheses 1, 2, and 3, I proposed a new Secured Payment design — ready for the next validation round: usability testing (UT) followed by a second A/B test before final rollout.
As one of MoMo e-wallet's core screens, Secured Payment supports a wide range of use cases. The design addresses two distinct user states:
Users without active Pay Later (pre-approved, unregistered)
Users with Pay Later activated (including Installment options)


Does the design solution fulfill the initial goals set out?
A/B Testing & Usability Testing
🔍 To validate the new design, we ran a two-stage validation:
Usability Testing (n=6) — qualitative check on comprehension, task success, and friction before committing to engineering build
A/B Testing — quantitative validation of conversion impact at scale, gated on UT findings
UT acted as a low-cost filter: issues caught here saved A/B test cycles and engineering rework.
Usability Testing
Group 1: User does not have a Pay Later account
Number of testing users: 2
For users without an active Pay Later account, the research team divided them into two groups and evaluated their activation journey and experience at the Secure Checkout screen. based on the scenarios outlined in the table below.
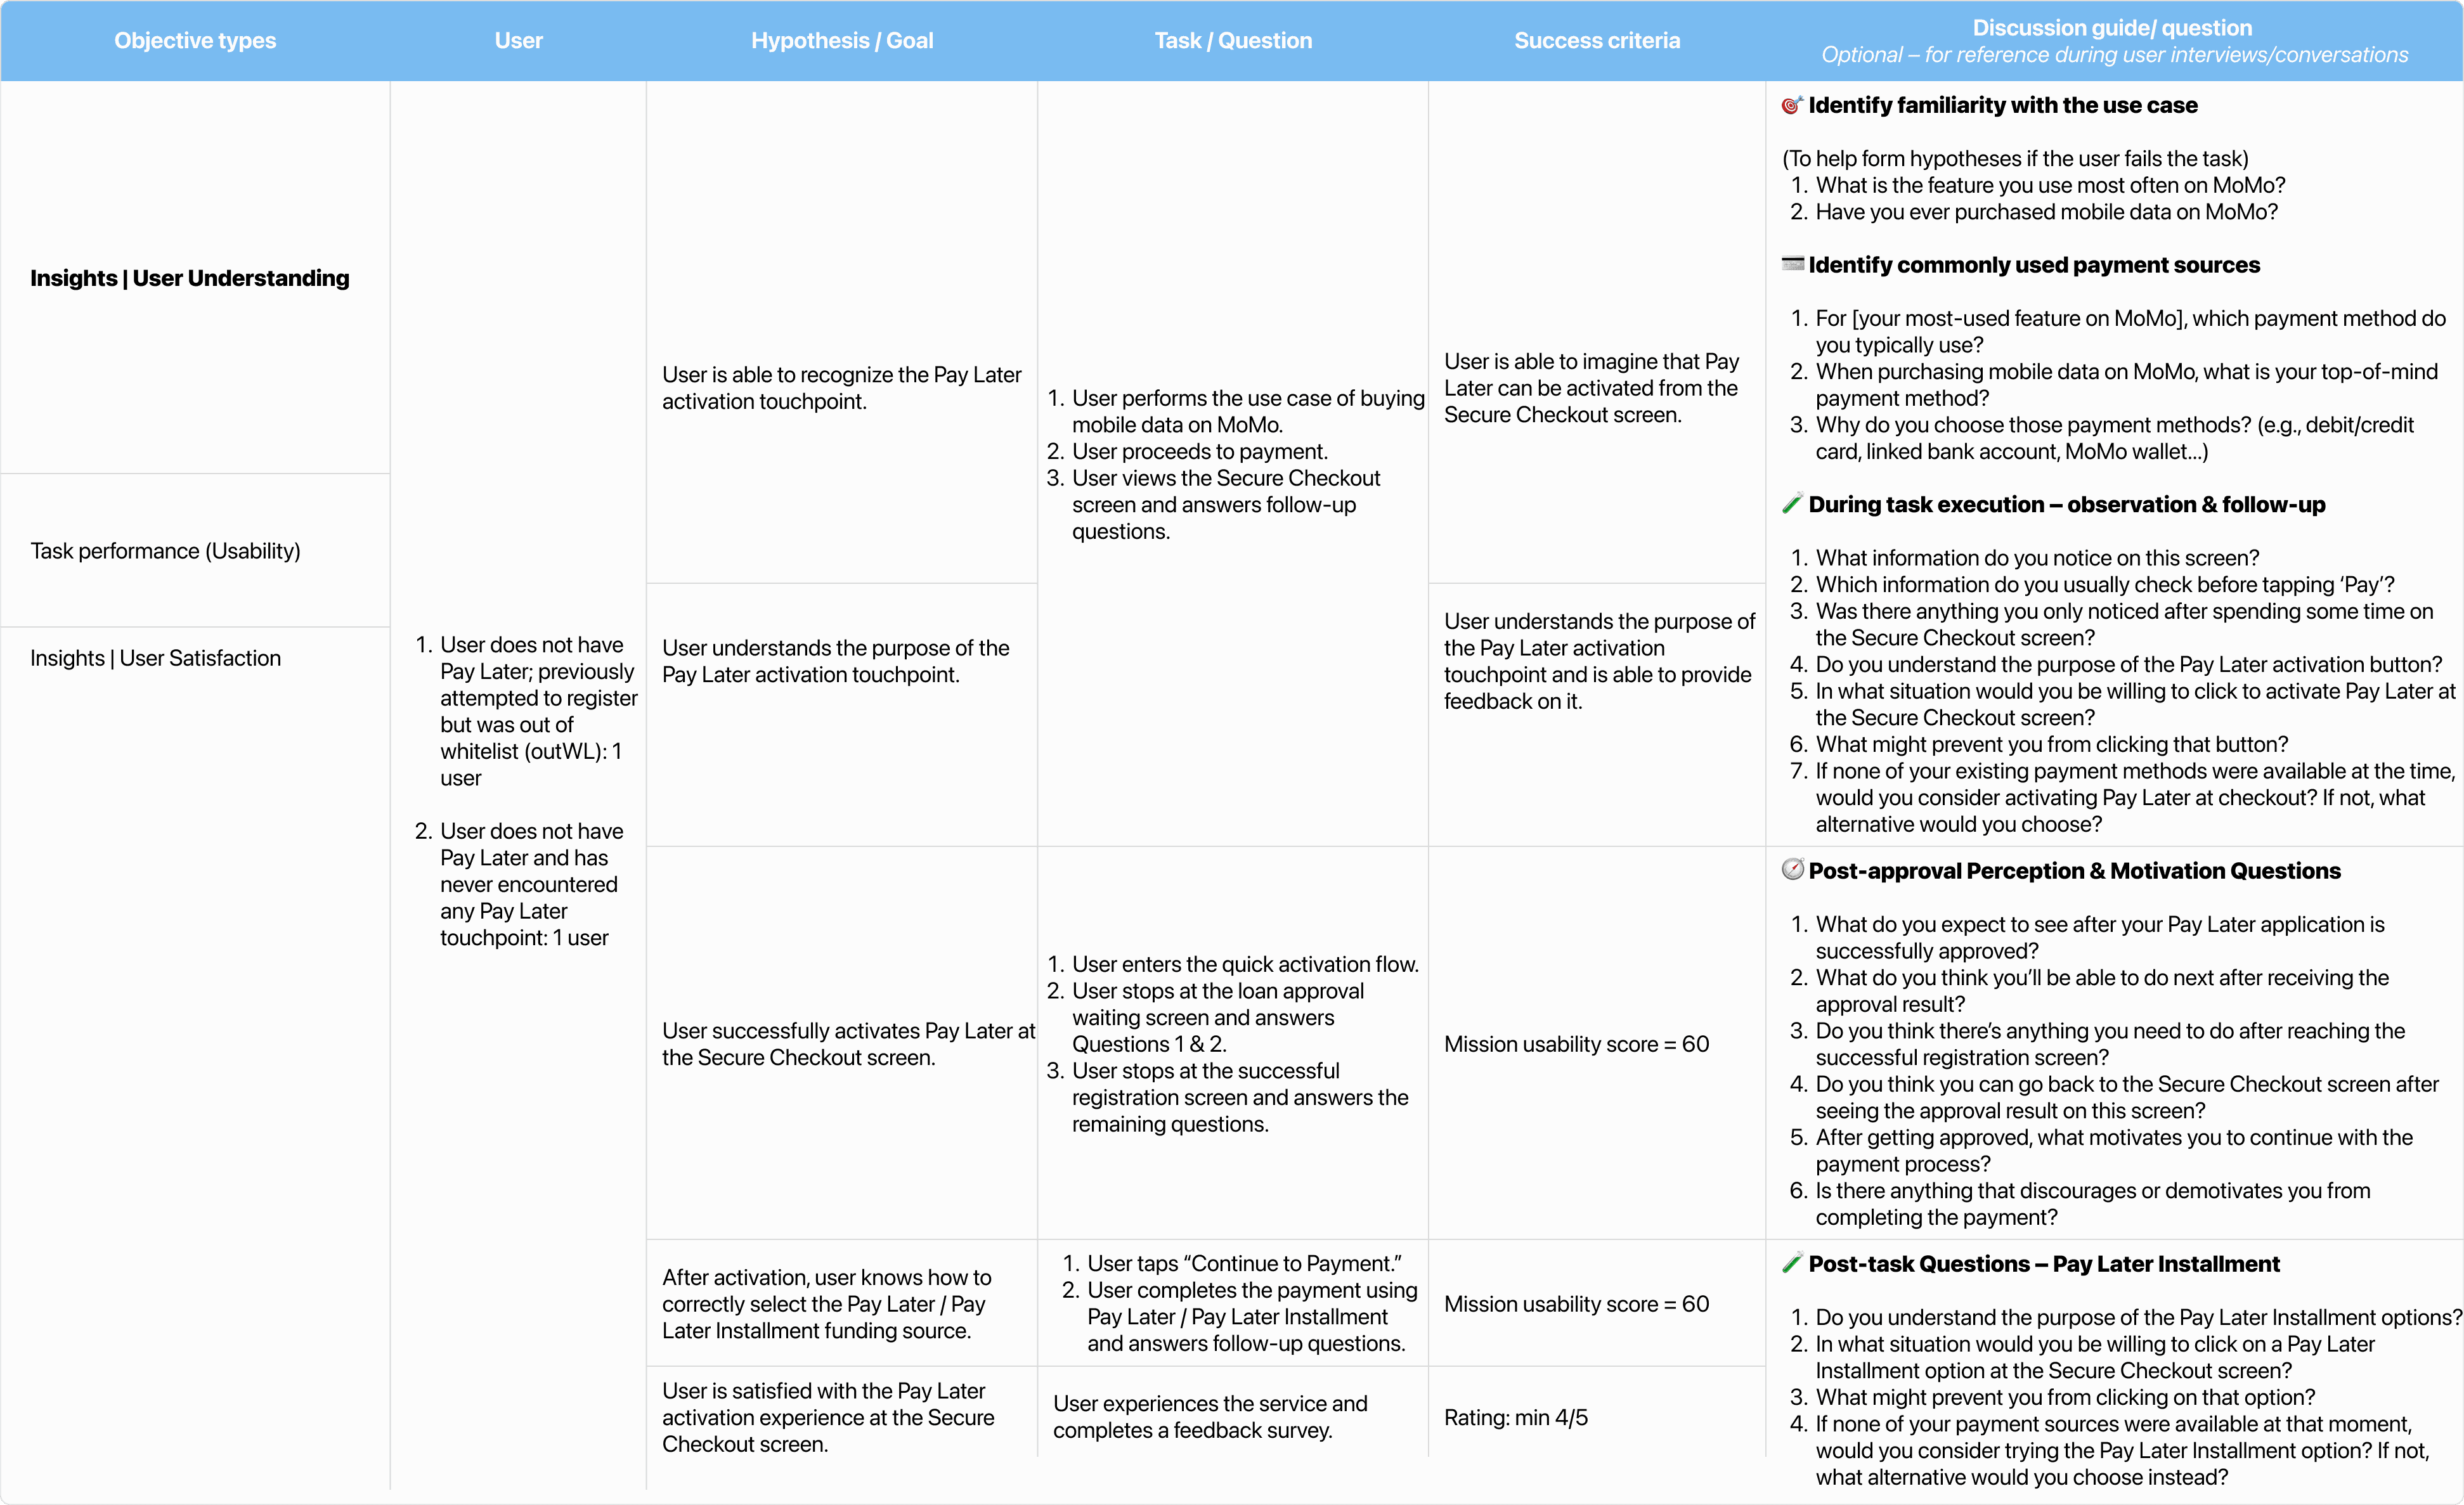
🗝️ Key Finding
Disclaimer: Due to project confidentiality and participant privacy, the detailed UT report is not included here.
Both pilot participants recognized the Pay Later touchpoint and completed activation. Both rated satisfaction 4/5. Usability score (80/100) noted as directional signal only — n=2 is below the threshold where standardized usability scoring carries statistical meaning.
Group 2: User has an active Pay Later account
Number of testing users: 4
For users who already have Pay Later, we conducted testing to observe how they select Pay Later and Pay Later Installment as payment methods, based on the scenarios outlined in the table below.

🗝️ Key Finding
Disclaimer: Due to project confidentiality and participant privacy, the detailed UT report is not included here.
Users could clearly distinguish and select between Pay Later and Installment options. While overall satisfaction was high (≥4/5), motivation to choose Installment depended on urgency or lack of other payment sources. Visibility and perceived value of Installment need improvement => Known limitation accepted for A/B test baseline; scoped for v2. (n=4 remains below Nielsen's recommended 5 for usability testing; findings treated as directional input to A/B test design, not standalone validation.)
UT surfaced no blocking issues for the core activation and payment flows across both user segments. One area flagged for monitoring — Installment perceived value — was carried forward as a secondary metric in A/B testing rather than a redesign trigger. Design handed off to engineering for A/B build.
A/B Testing
With friction factors now validated, this second A/B test measured whether the full redesign — combining all three fixes — delivered results at scale.
Test setup
Cohort: 10% pilot traffic on Secured Payment
Duration: 28/04/2025 - 25/05/2025 (4 weeks)
Treatment: New Secured Payment design (incorporating credit limit visibility + promotion block + clear CTA + restructured placement)
Control: Existing Secured Payment UI
Counter metric (test-level): Overall Secure Checkout conversion rate must not materially decrease
Two hypotheses were analyzed within this single test, each with its own analysis window based on data sufficiency:
Hypothesis 1
Analysis window: 28/04 - 25/05 (full 4 weeks for activation rate sufficiency)
Hypothesis 1: For users whose transactions meet the eligibility criteria to open MoMo Pay Later, if they are informed about the product and its value proposition on the Secured Payment screen, they will be more likely to consider using it.
This can help encourage users to register for MoMo Pay Later and make payments using it as the funding source.
📊 Metrics
- Success Metric: Increase in the number of new MoMo Pay Later activations
- Counter Metric: Conversion rate of Secure Checkout must not decrease
Test scope: 10% traffic pilot on Secured Payment, mutually exclusive cohort
Methodology note: Traffic split handled by the Payment Core data team; detailed statistical design available on request.
With friction factors now validated, this second A/B test measured whether the full redesign — combining all three fixes — delivered results at scale.
Hypothesis 2
Analysis window: 28/04 - 18/05 (3 weeks; unlock event volume reached sufficiency earlier)
Hypothesis 2: For users with a locked MoMo Pay Later account, if they have a payment need and clearly see the value of this funding source at the Secure Checkout screen — along with a quick unlock option — they are more likely to consider unlocking and continuing to use Pay Later.
📊 Metrics
- Success Metric: Number of users who successfully unlock MoMo Pay Later
- Counter Metric: Conversion rate of Secure Checkout must not decrease
Test scope: 10% traffic pilot on Secured Payment, mutually exclusive cohort
Methodology note: Traffic split handled by the Payment Core data team; detailed statistical design available on request.
Data & Result

Control

Treatment
Disclaimer: To ensure confidentiality, the data has been blurred and adjusted.

Table 4: A/B Test Results
📊 Key Results Summary
What the test validated
Activation rate (H1): Eligible users activated Pay Later 17% more often in Treatment vs Control
Unlock rate (H2): Locked users unlocked Pay Later at a rate of 4.27% in Treatment, vs 0.22% in Control — moving an effectively buried flow into a visible one
Pay Later usage: Conversion rate rose +2.01% at the user level and +0.33% at the transaction level — both directions positive
Counter metric (Secure Checkout): Conversion held at 1.51% (transactions) with a -0.03% shift among users — no meaningful drop in the core checkout funnel
How to read these numbers
The Treatment was a package — credit limit visibility, dedicated promotion block, and clear activation CTA worked together. The 17% lift validates the package as a whole; testing each element on its own is scoped for the next round.
H2's headline number can read as enormous in relative terms because the Control rate was nearly zero — the previous unlock path was deeply buried. The honest framing: the Treatment surfaced a path that didn't really exist before, rather than optimizing one that did.
What we're watching
Absolute new transactions (~5,700) and users (~2,500) are small relative to MoMo's monthly payment volume (in the millions) — expected from a 10% pilot over 4 weeks. The validated signal is the rate lift; mass rollout impact depends on whether the rate sustains across the broader traffic mix.
The small counter metric movement (-0.03% users) sits within normal fluctuation, but worth monitoring as the design rolls out to wider traffic.
Viable solution to tackle the situation!
Design Solution
New Secured Payment
To drive MoMo Pay Later adoption, the design evolved from a passive discovery model to an action-oriented experience. By restructuring the information architecture and highlighting immediate value, we transformed the checkout screen into a powerful conversion touchpoint."
Strategic UI Evolution: From Discovery to Conversion
Some use cases

Project Impact
From A/B Testing to 8-Month Post-Launch Results
Pay Later Growth
Internal SoF Share
trending_up
% to
%
(+4.8 pp)
Shifted user behavior to high-margin funding
sources.
Pay Later New Users
trending_up
~
business target met
Optimized touchpoints and reward flows drove full-year activation goal.
Figures adjusted to preserve confidentiality; magnitudes and directional trends reflect actual results.
What I’ve learned from this project
Key Takeaways
Key Takeaways
Designing for Secure Checkout requires balancing usability, user trust, and business objectives
The proposed solution improves information clarity and supports Pay Later activation
User satisfaction with the experience remains high across both variants
A clear CTA and simplified flow help reduce friction during payment
Iterative testing (Usability Testing → A/B Testing) is key to validating long-term impact
Special thanks to all the team members who contributed to this project. Your collaboration made this possible. 🙏
Thank you for taking the time to explore my little world!
👉 Connect with me:
nguyenhoangkhoic3b@gmail.com